Distressed Property Sales & Foreclosures in Cherry Hill
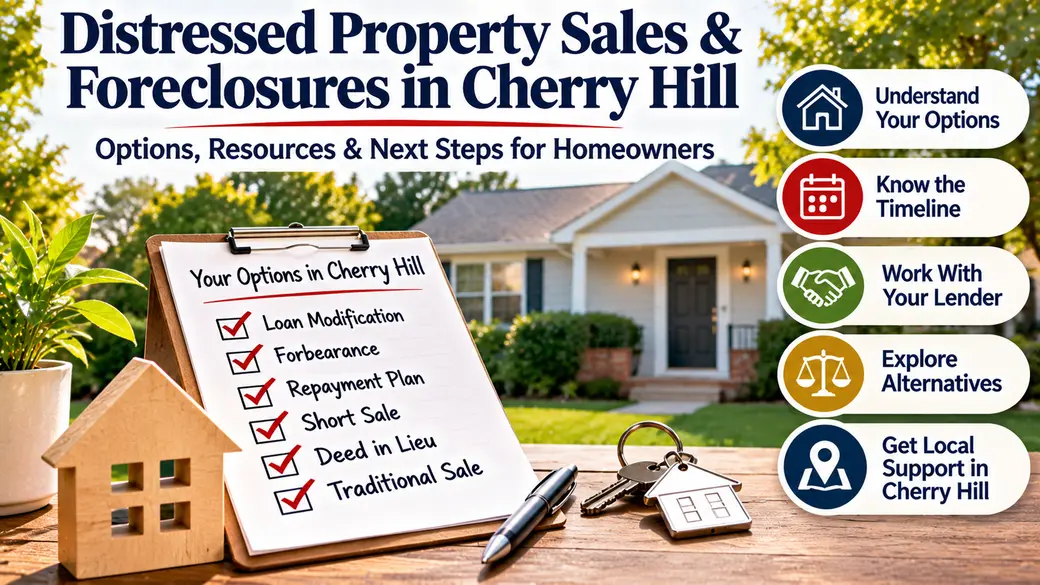
Distressed Property Sales & Foreclosures in Cherry Hill can often be addressed through an early sale, lender workout, or another negotiated path before a sheriff’s sale occurs. Financial hardship, missed payments, or a home in poor condition can make selling feel overwhelming, but you do not have to make decisions alone or under pressure.
This guide explains common options and places to seek help in Cherry Hill Township with an empathetic, non-judgmental approach. Every situation has different loan terms, deadlines, ownership details, and financial consequences, so timely guidance matters.
What Makes a Property "Distressed"?
A property is distressed when financial pressure, serious condition concerns, or both limit an owner’s choices. Financial distress may involve missed mortgage payments, lender notices, pre-foreclosure activity, or a pending foreclosure case. Physical distress can include substantial deferred maintenance, water damage, outdated systems, structural concerns, or repairs an owner cannot reasonably complete before selling.
A home does not need to be vacant or visibly deteriorated to be distressed. A well-kept Cherry Hill Township property can still be financially distressed when the owner is behind on payments or faces a deadline that narrows available choices.
The difference matters because financial distress creates a timeline, while physical distress affects buyer demand, pricing, and the work needed to close. In some cases, both issues need attention at the same time.
How Foreclosure Generally Works
Foreclosure is the legal process a lender may use to recover a property after a borrower defaults on a mortgage. It commonly begins with missed payments and communications from the lender, then can move through formal notices, legal filings, and a foreclosure sale if no resolution is completed.
New Jersey uses a judicial foreclosure process, meaning foreclosure actions proceed through the court system. That framework applies to Cherry Hill Township and other New Jersey communities. The process may involve Superior Court procedures, notices, opportunities to respond, and a sheriff’s sale, but the timing can differ based on the loan, court activity, communication between the parties, and any resolution pursued.
A notice or court document should be treated as time-sensitive. Read every document, retain records of lender communications, and seek advice from a qualified housing counselor or attorney who can explain the process as it applies to your circumstances.
Options Before Foreclosure
Homeowners may have several paths available before a foreclosure sale, depending on their finances, loan status, property equity, and lender requirements. A lender may consider a loan modification, temporary forbearance, repayment plan, short sale, or deed in lieu of foreclosure. In other situations, a traditional sale may provide a clearer outcome.
| Option | May fit when | Usually requires lender participation | Key consideration |
|---|---|---|---|
| Loan modification | Payments are no longer manageable under current terms | Yes | New loan terms and eligibility should be reviewed carefully |
| Forbearance | A temporary hardship affects the ability to make payments | Yes | Missed amounts may still need to be addressed later |
| Repayment plan | Income has resumed after a temporary setback | Yes | Monthly payments may be higher during the catch-up period |
| Short sale | Expected sale proceeds may be below the mortgage payoff | Yes | The lender must approve the transaction terms |
| Deed in lieu | Keeping or selling the home is no longer workable | Yes | The lender decides whether to accept the property transfer |
| Traditional sale | Expected proceeds can cover the payoff and transaction costs | Not usually, beyond payoff coordination | Timing, condition, and local buyer demand affect the outcome |
A traditional sale can be worth considering when the expected proceeds may cover the mortgage balance, closing costs, and other obligations. Homeowners considering a market sale can review the available information on selling a home before choosing an approach.
The best choice depends on facts that should be reviewed carefully, including the mortgage payoff, liens, property condition, anticipated timeline, and whether the lender must approve the outcome. No single solution fits every hardship situation.
Selling During Pre-Foreclosure
Selling during pre-foreclosure can preserve more control because an owner may still have time to choose a listing strategy, prepare disclosures, evaluate offers, and coordinate a closing. Acting earlier generally leaves more room to compare alternatives instead of responding to an immediate deadline.
A sale does not eliminate the need to communicate with the lender. Homeowners should keep the lender informed when appropriate, confirm payoff requirements, and make sure a proposed closing date is realistic. If there is limited equity or the balance may exceed expected proceeds, lender involvement may be necessary.
For a Cherry Hill homeowner, an early value review can clarify whether a conventional listing, an as-is sale, or a lender-approved short sale deserves closer consideration. It also creates time to organize documents and avoid decisions based solely on a single urgent offer.
Short Sales Explained
A short sale is a lender-approved transaction in which a property sells for less than the total amount owed on the mortgage. Because the lender must agree to the proposed terms, a short sale differs from an ordinary sale in which the seller can simply accept an offer.
Short sales can involve detailed financial documentation, a buyer who can remain patient during lender review, and clear communication among the seller, lender, and transaction professionals. Approval is not automatic, and the lender may establish conditions before the transaction can close.
The financial and legal effects can vary by household and loan situation. Homeowners should discuss their circumstances with qualified housing, legal, and tax professionals before deciding whether a short sale is appropriate.
Selling As-Is or Quickly
An as-is sale can be appropriate when a home needs substantial work, the owner does not have the funds or time for improvements, or a move must happen quickly. Selling as-is does not mean withholding known property information. Sellers should still provide required disclosures and describe the property accurately.
Speed can involve tradeoffs. Lower preparation demands may appeal to some buyers, but the home’s condition, buyer financing, and perceived repair scope can affect the offers received. Pricing should reflect the property’s present condition rather than an assumed value after renovations.
A clear plan helps sellers compare realistic choices: making selected repairs, selling in current condition, or adjusting timing if possible. The goal is not to create a perfect property, but to choose an approach that fits the owner’s finances, deadline, and ability to manage the process.
If your financial circumstances allow time for a traditional home sale, understanding the usual listing and preparation process can help you compare your options. From estimating selling costs to deciding which repairs are worthwhile, our guide to preparing and selling a starter home in Cherry Hill offers additional information for homeowners considering a move. Keep in mind that foreclosure deadlines and lender requirements may limit which selling strategies are available.
Pricing a Distressed Property
Pricing a distressed property requires an honest assessment of condition, urgency, local competition, and the likely buyer pool. A home with major repair needs may appeal to buyers with the resources and tolerance for improvement, while financial distress can create a timeline that affects how broadly the property can be marketed.
The price should account for visible condition concerns, deferred maintenance, comparable sales, and likely closing requirements. Overpricing can use valuable time when lender deadlines are approaching. Underpricing without a clear strategy can reduce the funds available to satisfy obligations at closing.
A current review of the property’s probable market position provides a practical starting point. In Cherry Hill Township’s higher-value segments, buyers may still expect a home to be positioned accurately when repairs, updates, or an unusual timeline are part of the transaction.
Buying Distressed Properties
Buying a distressed property can create an opportunity to acquire a home with renovation potential, but it also calls for careful budgeting and patience. Distressed listings can include homes sold as-is, lender-owned properties, or properties whose condition limits the available financing options.
Buyers should evaluate the complete cost, not only the asking price. Repairs, municipal requirements, carrying costs, financing terms, title questions, and the time required for improvements can all affect whether a purchase makes financial sense. A lower price does not automatically mean a better value.
Before making an offer, buyers should compare the property’s condition and intended use with their budget, lender guidance, and longer-term plans. MLS listing search results can help buyers identify available properties, but each home’s condition, ownership status, and transaction requirements should be evaluated individually.
Where to Get Help
Free or low-cost housing counseling can help homeowners understand foreclosure-prevention options, communicate with lenders, and organize next steps. The U.S. Department of Housing and Urban Development maintains a directory of HUD-approved housing counseling agencies.
Cherry Hill Township homeowners can also review New Jersey court resources to understand foreclosure mediation and case procedures. New Jersey’s foreclosure mediation program is intended to help homeowners and lenders explore a mutually acceptable resolution, while the foreclosure case may still continue during mediation.
Camden County Sheriff’s Office foreclosure-sales information explains that sheriff’s sales involve legal and property-specific risks and advises participants to consult an attorney for legal guidance. That public information can help explain the sale process, but it does not replace advice about an individual notice, title issue, loan balance, or deadline.
A real estate attorney can explain legal notices, deadlines, ownership questions, and transaction documents. A tax professional can help assess potential tax consequences connected to a sale, debt forgiveness, or other financial changes. The Consumer Financial Protection Bureau also provides foreclosure help for homeowners with information about lender communications and available assistance.
Explore Your Home Selling Options in Cherry Hill
Facing financial difficulties or considering selling a home that needs significant repairs can feel overwhelming. Val Gallagher of Legacy Homes Group | REAL Broker helps Cherry Hill homeowners review property values, selling timelines, and available options based on their circumstances.
Whether you're considering a traditional sale, an as-is listing, or a pre-foreclosure sale, explore your home selling options and connect with Val Gallagher for a confidential, respectful, and no-pressure conversation.
What you can expect when you reach out:
-
A confidential review of your situation and potential selling options
-
A current home value estimate to help compare your property's value with the amount owed
-
Guidance on finding appropriate housing counselors, attorneys, and lender loss mitigation resources
For foreclosure deadlines, loan modifications, or legal concerns, consult your lender, a HUD-approved housing counselor, or a qualified New Jersey attorney.
Can I sell my house if I'm behind on payments?
A homeowner may still be able to sell while payments are past due if the transaction closes before a sheriff’s sale and the lender’s payoff requirements are addressed. The available time, property value, loan balance, and any lender approval needs will shape the available path.
What is the difference between a short sale and foreclosure?
A short sale is a negotiated transaction in which the lender approves a sale price below the mortgage balance. Foreclosure is the court-based process through which a lender may take and sell a property after default when another resolution is not completed.
How long does foreclosure take?
The timing varies widely because state law, court procedures, lender actions, and the circumstances of an individual case all affect the process. In New Jersey’s judicial system, filings, responses, communications, and attempted resolutions may influence how a case progresses.
Where can I get free foreclosure help?
HUD-approved housing counseling agencies are an appropriate first resource for free or low-cost help reviewing options and preparing for lender conversations. New Jersey foreclosure mediation information may also be relevant for eligible homeowners facing a court foreclosure case.
Categories
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "