Distressed Home Selling: How to Sell When Your Situation Is Difficult
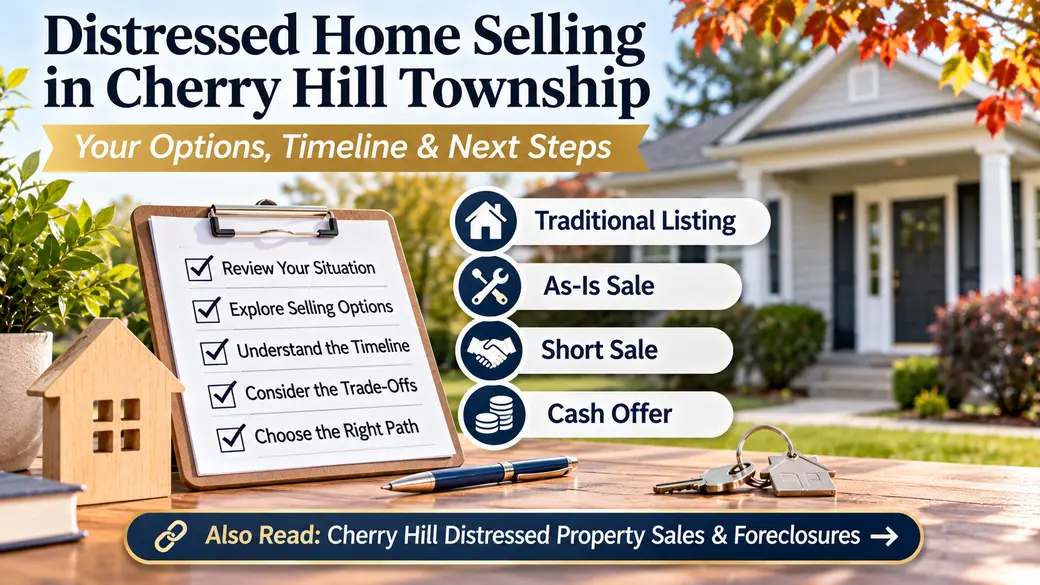
Distressed home selling does not mean you have no control. Job loss, divorce, illness, inherited repairs, missed payments, or an urgent move can create pressure, but you still have choices. A clear timeline, realistic home-value review, and comparison of each sale path can turn a difficult situation into a manageable plan.
Common Reasons Homeowners Sell Under Pressure
Homeowners sell under pressure when financial hardship, life changes, relocation, or major repairs make keeping the home difficult. The circumstances may be personal, temporary, or unexpected, but the need for a workable plan can be immediate.
Financial strain can involve reduced income, rising expenses, missed mortgage payments, or debts that have become harder to manage. Divorce may require a jointly owned property to be sold so each owner can move forward. A job transfer, family obligation, medical issue, or military relocation can also create a deadline that does not align with a conventional selling timeline.
Property condition is another common factor. Deferred maintenance, water damage, outdated systems, storm-related repairs, or a house filled with inherited belongings can make preparation feel overwhelming. In these situations, the goal is not necessarily to make the property perfect. It is to understand its present condition, likely market position, available time, and potential proceeds.
For a Cherry Hill Township homeowner, the right path depends on the home’s condition, ownership circumstances, financial obligations, and the date by which a move or closing needs to happen.
First Steps to Take
The first step is to organize your mortgage, property, ownership, and deadline information before making decisions under pressure. Clear records help you identify what needs to be resolved and whether you have time to pursue a broader marketing strategy.
Gather documents such as:
- Your latest mortgage statement and payoff information
- Payment records and notices from your loan servicer
- Property-tax and homeowners insurance records
- Documentation for significant repairs or known property conditions
- Information about liens, judgments, ownership changes, or debts connected to the home
- Estate, divorce, trust, or shared-ownership documents that could affect authority to sell
Write down every important date, including the next mortgage due date, any lender deadline, a court-related date, a relocation deadline, or a preferred move-out date. A written timeline can help distinguish between a situation that requires an immediate solution and one that allows time for a traditional listing.
If you are behind on payments, contact your lender early. Ask about your current payoff amount, required documents, and how a pending sale may affect your account. Keep notes from each conversation, including the date, representative’s name, and any deadlines discussed.
It can also help to confirm ownership and title-related details early with a qualified attorney or title professional. A lien, estate matter, divorce agreement, or co-owner signature requirement may affect the closing process, so identifying those items before accepting an offer can prevent avoidable delays.
Your Selling Options
The best distressed home selling option depends on your timeline, property condition, equity, and need for certainty. Traditional listings, as-is sales, short sales, and cash offers each involve different trade-offs.
| Sale path | When it may fit | Time and coordination | Main trade-off |
|---|---|---|---|
| Traditional listing | You have time for marketing, showings, and negotiations | Usually requires preparation, buyer access, and offer review | Broad exposure may support stronger terms, but the process can take longer |
| As-is sale | Repairs do not fit your budget or timeline | Requires clear condition disclosures and realistic pricing | Reduces upfront work, but buyers may account for needed work in their offers |
| Short sale | Expected proceeds may not cover the mortgage payoff and selling costs | Often involves lender review and added documentation | May provide a path forward, but timing and approval can be less predictable |
| Cash offer | Speed and fewer financing-related delays are the priority | Can move quickly if terms are clear and the buyer is credible | Convenience may come with a lower offer or less favorable net proceeds |
A traditional listing can expose the home to the broadest group of buyers. It may fit when you have enough time for marketing, showings, and negotiations. Even a home needing work may attract buyers when its price and disclosures accurately reflect its condition.
An as-is sale means marketing the property in its current condition rather than completing an extensive improvement list first. Known issues still need to be disclosed as required, but this route can reduce the need to spend money on updates that do not fit your budget or deadline.
A short sale may be considered if expected proceeds will not cover the mortgage balance and transaction-related costs. Because lender review is generally required, this path can involve more documentation and less predictable timing. Legal and financial guidance can help you understand the implications before selecting this route.
For Cherry Hill homeowners facing missed mortgage payments or possible foreclosure, understanding the available options early can help prevent rushed decisions. Lender requirements, property condition, outstanding debt, and legal deadlines may affect whether a traditional listing, short sale, or another approach is practical. For additional guidance, explore our closer look at foreclosure-related selling options in Cherry Hill before deciding how to proceed.
A cash offer can provide speed and reduce some financing-related delays, particularly when a property requires substantial work. Convenience may come with a lower offer, so compare the proposed price, closing date, contingencies, proof of funds, and estimated net proceeds rather than focusing only on the headline number.
A practical way to compare options is by timeline. If a closing is needed within roughly 30 days, sellers often prioritize certainty, clean terms, and a buyer’s ability to close. If there is more flexibility, a traditional listing or as-is marketing plan may offer more opportunity to compare buyer interest. If limited repairs are possible, focus spending on cleaning, access, safety, and visible maintenance rather than trying to complete a full renovation.
Understanding Your Equity
Equity is the amount that may remain after your home’s sale price is reduced by the mortgage payoff and selling costs. A sale price alone does not show what you may actually receive at closing.
Start with a realistic estimate of the home’s market value in its current condition. Then subtract the mortgage payoff, property-related debts that must be resolved, expected seller costs, and any concessions you may agree to during negotiations.
A higher offer with extensive requests or a delayed closing can provide less certainty than a lower offer with cleaner terms. At the same time, accepting the first fast offer without comparing estimated proceeds may leave money on the table.
A written net-proceeds comparison can make the decision easier to manage. It should show each possible sale price, anticipated costs, payoff amount, and estimated funds remaining. If likely proceeds may not cover the mortgage balance, speak with your lender and qualified legal or financial professionals before committing to a strategy.
Preparing the Home on a Budget
Low-cost preparation can improve buyer confidence without requiring a full renovation. Focus first on cleanliness, safety, access, and visible maintenance issues that may distract from the home’s overall potential.
Remove clutter, personal paperwork, unused furniture, and items that make rooms feel smaller. A deep clean, clear walkways, working light bulbs, and trimmed exterior areas can improve how the home appears in photographs and showings.
Prioritize affordable items buyers are likely to notice. Tightening loose hardware, replacing damaged outlet covers, touching up obvious paint marks, and addressing minor leaks can help the home feel better maintained. Avoid committing to major projects without considering whether the likely return supports your timeline and goals.
If significant repairs are outside your budget, be direct about the property’s condition. Buyers can still see value in a home that needs work when its presentation, pricing, and disclosures align with reality.
Protecting Yourself From Scams
You can reduce the risk of foreclosure rescue scams by slowing down, verifying every party involved, and refusing to sign documents you do not understand. Pressure can make a promised solution sound convincing, so independent review is especially important.
Be cautious if someone guarantees a specific outcome, claims they can stop foreclosure immediately, asks for large upfront fees, or insists that you sign paperwork without time to read it. The Consumer Financial Protection Bureau identifies upfront-fee requests, guaranteed results, deed-transfer requests, and instructions to send payments somewhere other than your mortgage servicer as warning signs in its foreclosure scam guidance.
Do not rely on verbal promises about sale proceeds, moving assistance, or a future right to repurchase the home. Ask for all terms in writing, read them carefully, and consult an attorney before signing an agreement affecting ownership, debt, or your right to remain in the property.
A legitimate offer should allow time to compare terms. If a buyer, investor, or service provider says you must decide immediately, treat that pressure as a reason to pause.
Getting Support
The right support can help you evaluate a difficult sale without making decisions alone. Depending on your circumstances, you may need housing counseling, legal guidance, lender communication, tax advice, and a real estate strategy that fits the property and your timeline.
A HUD-approved housing counselor may help homeowners understand options, organize finances, and communicate with a lender. An attorney can help explain documents, ownership questions, divorce-related property matters, inherited-property concerns, or possible debt consequences. A tax professional can address questions involving proceeds and future obligations.
A local real estate professional can provide a structured comparison of value, timing, property condition, and sale terms. Reviewing home-selling options alongside your financial and legal considerations can help you identify a path that fits the home and your deadline.
Conclusion
Distressed home selling becomes more manageable when you replace uncertainty with a written plan. Gather your documents, understand your timeline, compare your equity and estimated proceeds, and evaluate each option based on its actual terms.
You do not need to solve every issue at once. Start with the next practical step, whether that is contacting your lender, organizing property records, seeking legal guidance, or reviewing how a sale could work in Cherry Hill Township.
Selling under pressure? Val Gallagher of Legacy Homes Group | REAL Broker helps homeowners in Cherry Hill compare their selling options and move forward with confidence through a confidential conversation.
What you get when you reach out:
- A confidential consultation about your options and timeline
- A home value estimate and net proceeds comparison
- A selling plan that fits your budget and situation
FAQ
What is a distressed home sale?
A distressed home sale is a property sale shaped by financial strain, a major life event, an urgent deadline, or serious condition concerns. Sellers may evaluate a traditional listing, an as-is sale, a short sale, or a cash offer based on their circumstances.
Can I sell my house if it needs major repairs?
Yes, a home with substantial repair needs can often be sold when its price, marketing, and disclosures accurately reflect its current condition. Some sellers complete limited affordable work, while others market the property as-is to buyers prepared to take on improvements.
How do I avoid foreclosure rescue scams?
Avoiding foreclosure rescue scams starts with refusing upfront-fee demands, reading every document, and seeking legal advice before transferring ownership or accepting a complex agreement. A credible party should provide enough time for you to understand and compare the terms.
Should I talk to my lender before selling?
Yes, reaching out to your lender early can clarify your payment status, payoff amount, deadlines, and any requirements if anticipated proceeds may not cover the mortgage balance. Keep written notes and records from each conversation.
Categories
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "